

21 Accounting Interview Questions You Must Know Before Your Next Interview - Part 1


30-Second Summary
Knowing the basics of accounting is very essential if you are preparing for an accounting job interview. Interviewers often check your understanding of fundamental accounting principles including the accounting principles, the golden rules, debit & credit, journal, ledger & trial balance, depreciation, working capital, BRS, balance sheet, capital expenditure & revenue expenditure. This blog discusses 21 basic accounting interview questions and answers that will help freshers, students and aspiring accounting professionals get ready with confidence for their next interview.
Let’s Explore 21 Essential Accounting Interview Questions
1. What is Accounting?
Answer: Accounting is the systematic process of recording, summarising and reporting of financial transactions. It helps a business to keep a track of all important financial transactions like sales, receipts, payments, purchases, deposits etc and keeping their record, summarising them and making reports for organisations. These records are kept to calculate various financial information during month end and when exchanging information with other businesses.
2. What are the Golden Rules of Accounting?
Answer: There are three golden rules:
- Personal Account: Debit the Receiver, Credit the Giver
- Real Account: Debit What Comes In, Credit What Goes Out
- Nominal Account: Debit All Expenses & Losses, Credit All Incomes & Gains
3. What is the difference between Debit and Credit?
Answer: Every accounting transaction has two sides which are Debit and Credit. Debit is the recording of what the business receives or spends. Credit is the recording of what the business gives or earns. Every transaction has at least one debit entry and at least one credit entry. The total amount of debits always equals the total amount of credits.
4. What is a Journal?
Answer: The first book of entry where business transactions are recorded as they occur is known as a Journal. It records the debit and credit entries prior to posting to the ledger.
For example, when a business pays cash for buying furniture costing ₹20,000, the transaction is recorded first in the journal.
5. What is a Ledger?
Answer: A ledger is a book in which journal entries are classified account-wise. It helps us to know what the balance of each account like Cash, Sales or Bank is.
Example: All cash transactions are posted to the Cash Account in the ledger so that the cash balance can be readily found.
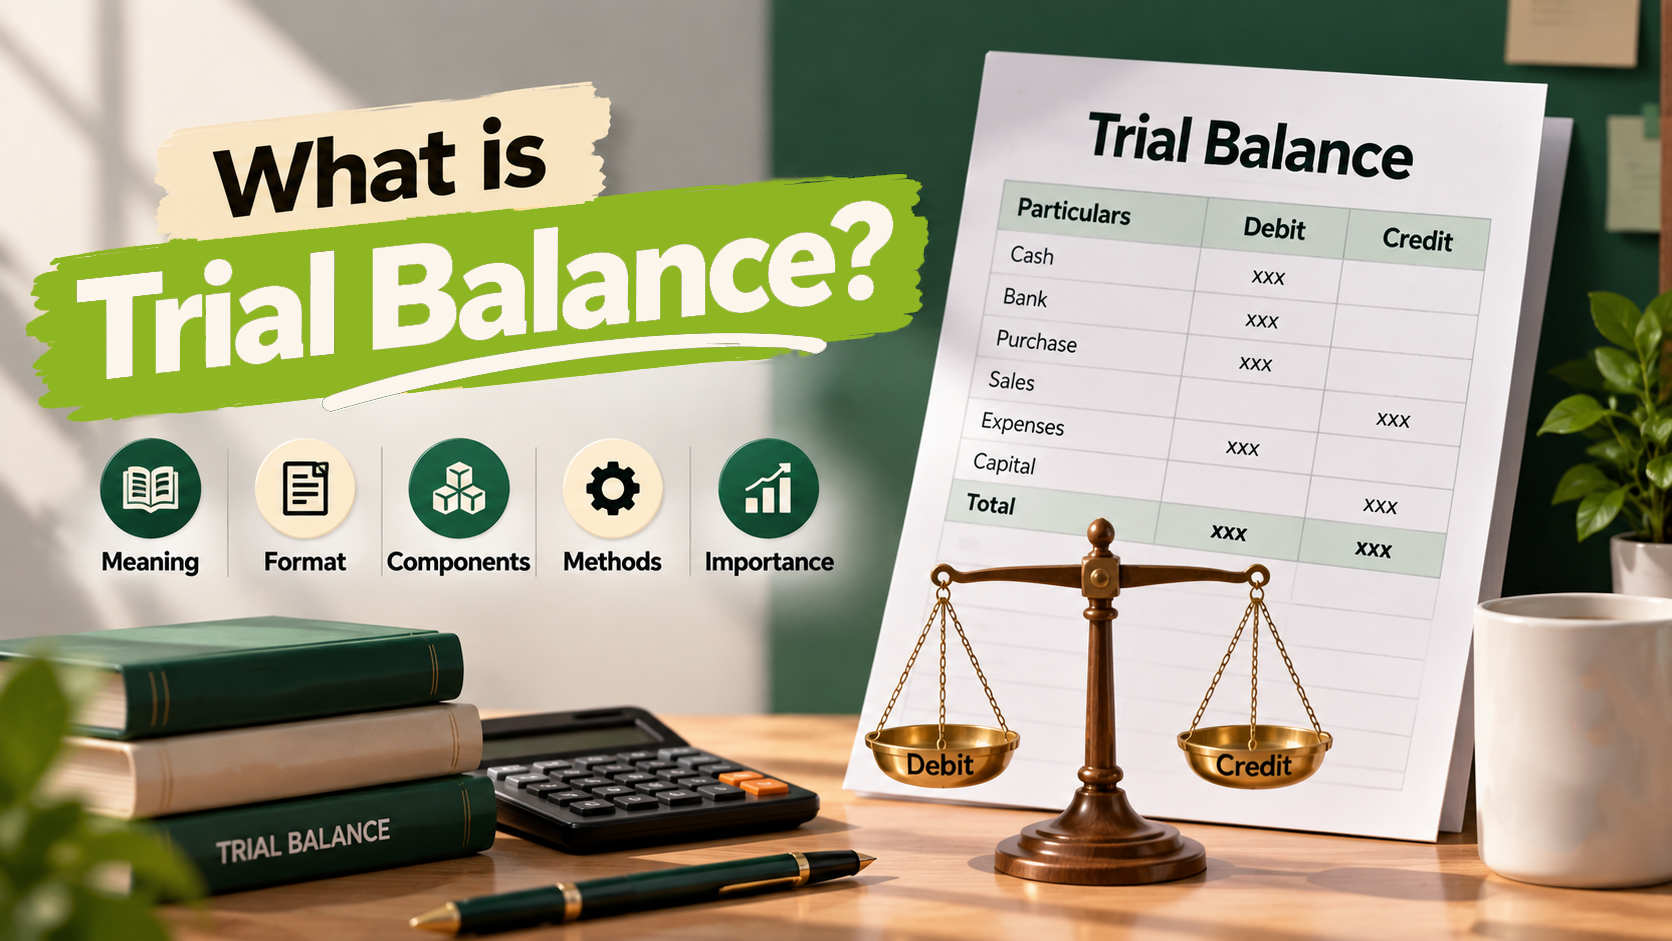
6. What is a Trial Balance?
Answer: Trial Balance is a statement prepared to verify the equality of the total of debit balances and the total of credit balances. This is made before the financial statements. For example, if the total debit is ₹5,00,000 then the total credit should be same i.e. ₹5,00,000.
7. What is Depreciation?
Answer: Depreciation is the reduction in the value of a fixed asset over time due to normal use, wear and tear, or obsolescence. Example: A machine purchased for Rs 1,00,000 may lose its value each year due to its usage.
8. What is the difference between Capital Expenditure and Revenue Expenditure?
Answer: Capital Expenditure is money spent on purchasing or improving long term assets which benefit the business for many years.
Example: Buying a machine or building.
Revenue Expenditure is money spent on day to day running of the business.
Example: Electricity bill, rent, salaries, office stationery etc.,
9. What is a Bank Reconciliation Statement (BRS)?
Answer: A Bank Reconciliation Statement is prepared to ascertain the difference between the balance of the bank as per the books of the company and the balance of the bank statement.
Example: The company may have issued a cheque which has not yet been presented to the bank, thus causing a difference in balances.
10. What is working capital?
Answer: Working capital is the cash you need to run a business day to day. That’s Current Assets minus Current Liabilities. Example: Current assets = 5,00,000
Current liabilities = 3,00,000
Working Capital = 5,00,000 – 3,00,000 = 2,00,000
11. What is the difference between accounts receivable and accounts payable?
Answer: Accounts receivable is the money owed to the business by customers.
Accounts payable is the amount of money that the company owes to its vendors.
For example:
You sold goods on credit = Accounts Receivable.
You purchased goods on credit = Accounts Payable.
12. What is deferred revenue?
Answer: Deferred revenue is cash you collect from a customer before you provide them with goods or services. Until the work is done, it’s a liability.
13. What is capital budgeting?
Answer: Capital budgeting is the process of deciding whether a business should invest in a long-term asset or project.
Example: A firm might consider whether purchasing a new machine will increase output and profits.
14. What is a balance sheet?
Answer: A Balance Sheet is a statement of a business’s assets, liabilities and capital as at a specific date.
15. What is the difference between direct and indirect costs?
Answer: a) Direct Cost is the cost which is directly related to the production of a product or the delivery of a service.
Example: Raw materials and wages in factory.
b) Indirect Cost is a cost that is necessary to run the business, but it cannot be attached to one specific product.
Example: Office rent, electricity, and administration salaries.
16. What is inflation?
Answer: Inflation is when the cost of goods and services goes up over time, meaning that your money doesn’t buy as much as it used to.
Example: If a litre of milk costs ₹50 today and ₹55 next year, the increase in price is due to inflation.
17. What is GDP?
Answer: GDP (Gross Domestic Product) is the total value of all goods and services produced within a country during a specific period, usually one year. It is used to measure economic growth of the country.
Example: If industries, farms, and service businesses together produce goods and services worth ₹300 lakh crore in a year, that contributes to the country’s GDP.
18. What is fiscal policy?
Answer: Fiscal policy means the government uses taxes and its spending to influence the economy. If the economy is slow, the government may spend more or reduce taxes. If prices are rising too fast, it may increase taxes or reduce spending to control inflation.
Example: The government may reduce taxes or increase spending to encourage economic growth.
19. What are the two types of fiscal policy?
Answer: a) Expansionary Fiscal Policy – The government increases spending or reduces taxes to boost economic activity and create jobs.
Example: Building highways, schools, or hospitals during a recession.
b) Contractionary Fiscal Policy -The government reduces spending or increases taxes to slow down the economy and control inflation.
Example: Increasing taxes when inflation is very high to reduce excessive spending.
20. What are liquid assets?
Answer: Liquid assets are assets that can be quickly converted into cash without losing much of their value.
Example: Cash, Bank Balance or Short-term investments
21. Who is a Sleeping Partner?
Answer: A sleeping partner is a partner who invests money in a business and shares in the profit or loss but who does not participate in the management of the business on a day-to-day basis.
Example: Mr. A invests ₹10 lakh in a partnership firm but does not participate in its day-to-day operations. He is a sleeping partner.
From Preparation to Confidence
The first step to acing an accounting interview is to have a strong understanding of accounting fundamentals. This blog has 21 questions that will assist you in revising essential concepts like debit and credit, journal, ledger, trial balance, depreciation, BRS, working capital, and balance sheet. Use these questions for a quick revision before your next interview. Instead of memorising the answers, try to understand the concepts and relate it to real business transactions.
Upgrade your practical accounting skills and knowledge of accounting software to be better prepared.
Next accounting interview? Having strong fundamentals and regular practice will make you feel more confident.

Nita R
Nita is a content writer specialising in Accounting, Finance, GST, and Taxation. She creates easy-to-understand, research-driven content that simplifies complex financial and tax concepts for learners, professionals, and businesses. Her expertise lies in translating technical accounting and GST topics into practical insights, helping readers stay informed about tax compliance, financial processes, and industry best practices. Through her content, she aims to make accounting and taxation accessible, accurate, and relevant for today's evolving business environment.