

What is Trial Balance? Meaning, Format, Components, Methods & Importance


30-Second Summary
How do you know whether your books are mathematically balanced? A Trial Balance gives you a quick check. It brings together the debit and credit balances of all ledger accounts at a particular date and helps check the arithmetical accuracy of bookkeeping. In this blog, we’ll explore what a Trial Balance is, what it includes, how it works, and why matching debit and credit totals does not always mean that the books are completely error-free.
Introduction
All businesses are required to maintain proper accounting records. First, transactions are entered in the books of accounts and then classified into respective ledger accounts. But how does a business know that the debit and credit entries have been entered properly?
This is where a Trial Balance can help.
A trial balance is the sum of the closing balances of all the ledger accounts at a particular date. Summary of the balances. It checks whether the total debit balances are equal to the total credit balances. It also connects the bookkeeping function with the preparation of the financial statements. After preparing the Trial Balance and making all the necessary adjustments, the business can then use the information to prepare the financial statements such as the Trading Account, Profit and Loss Account and Balance Sheet, depending on the applicable accounting framework and type of business.
Let us understand the meaning, format, components, importance and limitations of a trial balance.
What is Trial Balance?
Trial Balance is a statement showing the debit and credit balances of ledger accounts as on a particular date.
The basic concept behind a trial balance is based on the double-entry bookkeeping system where every accounting transaction has an equal debit and credit effect.
For example, suppose a business buys furniture for ₹20,000 in cash. Furniture Account is debited to the extent of ₹20,000. Cash Account is credited to the extent of ₹20,000.
All transactions are recorded and posted to their respective ledger accounts. The balances of all the ledger accounts are posted to the trial balance.
The main objective is to verify whether:
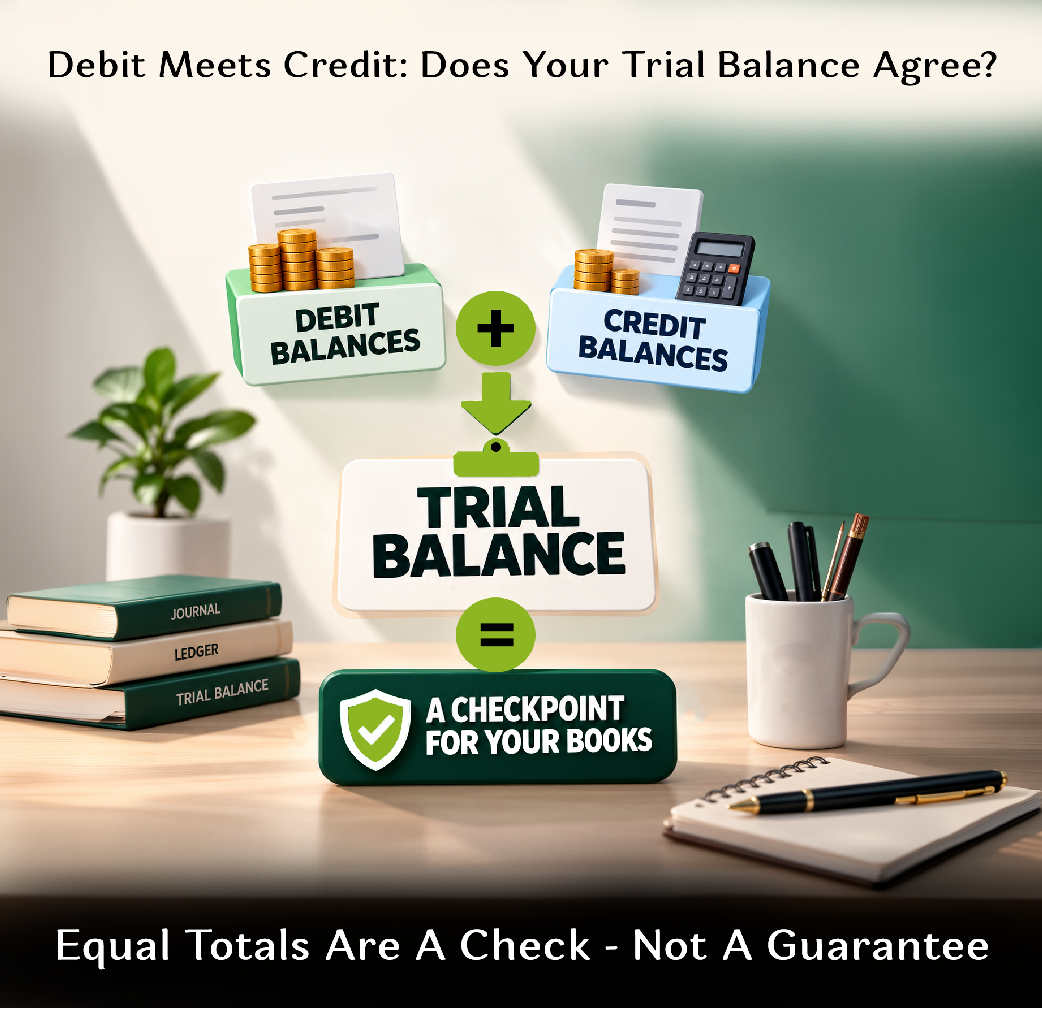
Total Debit Balances = Total Credit Balances
If the two totals match it means the books are arithmetically correct, but it does not mean that the accounts are free from error.
Why Is Trial Balance Important?
Trial Balance is an important part of the accounting process.
- Check the Maths: This helps identify any mathematical or posting errors that cause the debit and credit totals to be different.
- Summarises the Ledger Balances: Rather than reviewing each ledger account individually, accountants can see the balances of all accounts on a single statement.
- Assists in Preparing Financial Statements: The trial balance contains the basic accounting data to prepare the financial statements.
- Helps to Identify Certain Accounting Errors: The trial balance is useful to detect errors like wrong totalling, posting half amount or entering different amounts on debit and credit side.
- Helps Financial Analysis: A well-prepared trial balance provides accountants with an organised summary of account balances, making it easier to review the books before preparing financial statements.
What is Included in a Trial Balance?
A Trial Balance contains the closing balances of all ledger accounts for a particular accounting period. These balances are grouped into two columns such as Debit and Credit usually used to check whether the total debits and credits are equal.
A typical Trial Balance includes the following details:
| Particulars | What it Shows |
|---|---|
| Account Number / Ledger Folio | The account number or ledger reference used to identify the account. |
| Account Name | The name of the ledger account, such as Cash, Purchases, Sales or Capital. |
| Debit Balance | The closing balance of an account that appears on the debit side. |
| Credit Balance | The closing balance of an account that appears on the credit side. |
Simple Trial Balance Format
A Trial Balance can be presented in a simple format like this:
| Trial Balance as on [Date] | Debit (₹) | Credit (₹) |
|---|---|---|
| Cash | 50,000 | Nil |
| Purchases | 1,00,000 | Nil |
| Furniture | 30,000 | Nil |
| Sales | Nil | 1,50,000 |
| Capital | Nil | 30,000 |
| Total | 1,80,000 | 1,80,000 |
In this example, the total debit balance is ₹1,80,000, and the total credit balance is also ₹1,80,000. This indicates that the debit and credit balances are equal at the Trial Balance level.
The exact format and presentation of a Trial Balance may vary depending on the accounting system, reporting requirements and needs of the business.
Understanding the Components of a Trial Balance
- Name of Account: This column contains the names of the ledger accounts to be included in the balances.
For example:
• Cash Account
• Bank Account
• Sales Account
• Purchase Account
• Capital Account
• Machinery Account
- Ledger Folio Number: The ledger folio refers to the page or location of the corresponding ledger account. It helps an accountant find a balance in the right ledger.
- Debit Balance: The debit column of accounts with debit balances are debited.
Typical examples are:
• Cash Payment
• Bank
• Purchases
• Furniture (optional)
• Tools
• Lease
• Wages
• Accounts receivable
- Balance of Credit: Credit balances will be displayed in the credit column.
Typical examples are:
• Capital
• Sales
• Payable
• Commission earned
It is contingent upon the types and the balance of respective ledger accounts.
How to Prepare a Trial Balance?
Generally, the preparation of trial balance is done by following steps:
Step 1: Log your Transactions: Business transactions are first recorded in the right books of account in accordance with the principles of double-entry bookkeeping.
Step 2: Record Transactions in the Ledger Accounts: The transactions are then sorted and posted to the appropriate ledger accounts.
Step 3: Compute Ledger Balances: At the end of each accounting period or reporting date the debit and credit sides of each ledger account are totalled and the balance is determined.
Step 4: Posting Balances to the Trial Balance: Debit balances are put in the debit column and credit balances in the credit column.
Step 5: Add Both Columns: The debit and credit columns are totalled.
Want hands-on practice preparing trial balances and ledgers using industry tools? Check out Tally Education’s practical accounting courses
Does an Agreement of Trial Balance Mean There Are No Errors?
Short answer: Not necessarily.
This is one of the most important points to understand about a Trial Balance.
When the total of the debit column equals the total of the credit column, the Trial Balance is said to agree. However, this does not guarantee that every transaction has been recorded correctly. Some accounting errors may not affect the equality of the debit and credit totals.
For example:
- Error of Omission: If a transaction is completely omitted from the books, neither the debit nor the credit side is recorded. As a result, the Trial Balance may still agree even though a transaction is missing.
- Error of Principle: An error of principle occurs when a transaction is recorded in an incorrect type of account. For example, the purchase of machinery may be recorded as a purchase expense. Since both the debit and credit entries are still made, the Trial Balance may continue to agree.
- Compensating Errors: Sometimes, two or more errors may offset each other. For example, if one account is understated by ₹1,000 and another is also understated or overstated in a way that compensates for the difference, the debit and credit totals may still match.
Therefore, an agreed Trial Balance provides evidence of arithmetical accuracy, but it does not prove that the books are completely free from errors. Other accounting checks and procedures are needed to identify errors that do not affect the Trial Balance.
What are the Methods for Preparing a Trial Balance?
There are three common ways to do this:
- Complete Method: In this method, the total of debit and credit sides of each ledger account is taken to the trial balance.
- Balance Method: In the balance method only the closing debit or credit balance of each ledger account is shown. This is the general method used to prepare a trial balance.
- Total and Balance Methods: This method combines both the techniques by showing the totals as well as the closing balances of the ledger accounts.
Trial Balance vs Balance Sheet
A trial balance and a balance sheet are used for different purposes.
| Trial Balance | Balance Sheet |
|---|---|
| List of ledger account balances | Shows the financial standing of a business |
| Used to verify arithmetic correctness | Assets, liabilities and equity used to report |
| Prepared as a statement to support the preparation of financial statements | Prepared in conjunction with financial statements |
| Includes credit and debit balances | Presents assets, liabilities and equity in compliance with the relevant framework |
Hence the trial balance is an important accounting working statement, and the balance sheet is a formal financial statement.
Bringing the Books Together with a Trial Balance
A Trial Balance brings together the balances of ledger accounts and checks whether the total debits and credits agree. It provides an important checkpoint before financial statements are prepared and helps in reviewing accounting records.
However, an agreed Trial Balance does not mean the books are completely error-free, as some accounting errors may remain undetected. Understanding how to prepare, check and interpret a Trial Balance is therefore an essential skill for accounting students, business owners and professionals building a strong foundation in bookkeeping and financial accounting.
Frequently Asked Questions (FAQs)
Question 1: What do you mean by Trial Balance?
Answer: A Trial Balance is a statement of debit and credit balances of ledger accounts at a particular date for checking the arithmetical accuracy of bookkeeping.
Question 2: What is the primary purpose of Trial Balance?
Answer: The main purpose of the trial balance is to check that the total of the debit balances and the total of the credit balances are equal. It provides a summary of ledger balances.
Question 3: What are the main parts of Trial Balance?
Answer: The main components are usually: account name, ledger folio, debit balance, credit balance.
Question 4: What is the difference between trial balance and balance sheet?
Answer: A Trial Balance is a listing of ledger balances and is used to check the arithmetic accuracy of ledger postings. A Balance Sheet shows the financial position of a business by way of its assets, liabilities and equity.
Question 5: Does a Trial Balance ensure that there are no errors in the accounting?
Answer: No. An agreed trial balance doesn’t pick up all types of accounting errors. Errors of principle, complete omission, and compensating errors may go undetected.
Question 6: When is a Trial Balance prepared?
Answer: A Trial Balance is prepared generally at the end of an accounting period or on a particular date of reporting after posting of ledger accounts and ascertaining their balances.
Question 7: Where can I learn how to prepare a trial balance professionally?
Answer: Tally Education offers structured accounting and Tally courses covering trial balance preparation, ledger posting, and financial statement fundamentals for students and working professionals.

Nita R
Nita is a content writer specialising in Accounting, Finance, GST, and Taxation. She creates easy-to-understand, research-driven content that simplifies complex financial and tax concepts for learners, professionals, and businesses. Her expertise lies in translating technical accounting and GST topics into practical insights, helping readers stay informed about tax compliance, financial processes, and industry best practices. Through her content, she aims to make accounting and taxation accessible, accurate, and relevant for today's evolving business environment.